

USD
The dollar needs a fresh catalyst and the calendar does not supply one.
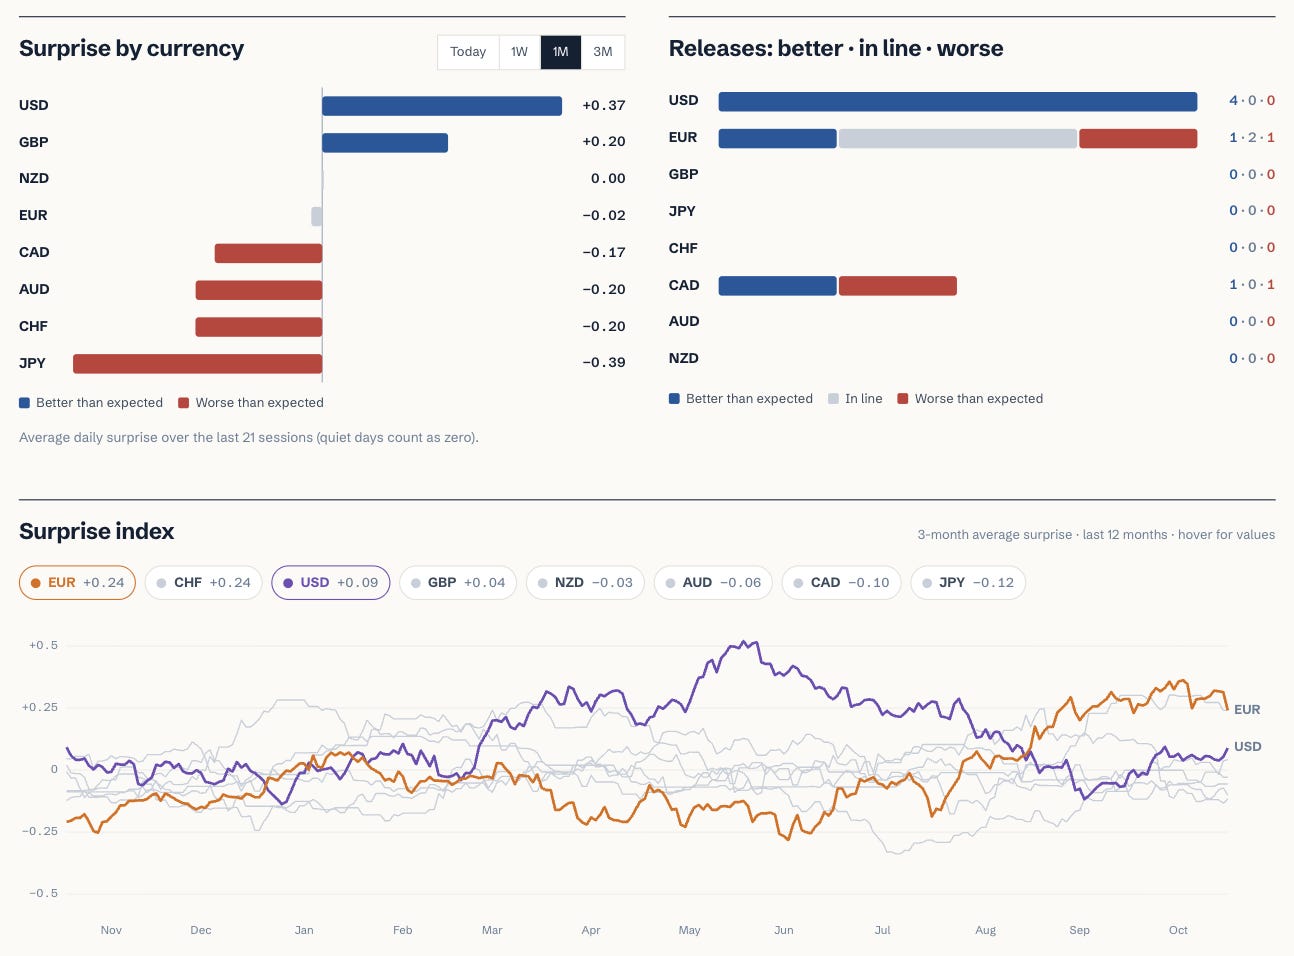
September inflation ran hot on both the consumer and the producer side, yet the dollar could not hold its gains. The Fed chair offered no forward guidance, front-end yields drifted lower and the AI-led equity sell-off pulled flows towards other markets. Futures price only around a 16% chance of a hike on 28 October but close to a full move by December. The blackout period has started, so the US inputs are limited to housing data, Thursday's jobless claims and Friday's flash PMIs. With front-end support capped until the meeting, the dollar looks vulnerable against currencies backed by hawkish central banks. Overall skew: soft vs GBP and NZD, neutral vs EUR.
EUR
France caps the euro more than the ECB supports it.
The ECB holds the deposit rate at 2.50% and has played down an October hike, citing the rise in long-term yields as a brake on growth. Markets lean towards a December move instead. The OAT-Bund spread remains near its widest since 2011-12, and Moody's reviews France's Aa3 rating with negative outlook on Friday. A downgrade would hit the euro harder than an unchanged outlook would help it. Friday's flash PMIs (manufacturing prior 52.9, services prior 53.0) matter mainly for their price components, while Tuesday's ZEW gives an early read on sentiment. Overall skew: soft vs GBP and CHF, neutral vs USD.
GBP
Wednesday's CPI decides how firmly November is locked in.
Headline inflation is expected at 3.4% from 3.1%, above the BoE's own forecast, and markets price about 77% for a hike to 4.0% on 5 November. Tuesday's labour data and Friday's retail sales come second. The Autumn Budget on 28 October adds fiscal risk, but a central bank turning hawkish into rising inflation is the stronger force. Overall skew: firm vs EUR, constructive vs USD.
JPY
The yen stays weak until the BoJ commits to a date.
Markets give a hike on 30 October little chance and price December at about 75%. That leaves the yen exposed to higher global yields and weaker local equities. Friday's national CPI should rise sharply from 1.9% after Tokyo core reached 2.7%, and a firm print strengthens the December case. Governor Ueda has flagged the weak yen as an inflation risk, so intervention talk stays alive. Overall skew: soft, with intervention risk limiting the downside.
CHF
The franc remains the cleanest European hedge.
Haven demand linked to French fiscal stress keeps EUR/CHF heavy near 0.927. The SNB holds at 0% and sees no need to change policy, and Thursday's minutes are unlikely to alter that view. Overall skew: firm vs EUR, neutral vs USD. A Moody's downgrade on Friday would bring the 0.92 area into play.
AUD
The labour market has taken a November hike off the table.
Employment fell 39.3k in September and unemployment rose to 4.7%, cutting the odds of a November hike to between 10% and 15%. Thursday's flash PMI is the only domestic release, so the real test is the Q3 CPI on 28 October. Until then the Aussie trades off Monday's China data and equity sentiment. Overall skew: soft vs NZD, neutral vs USD.
NZD
Wednesday's Q3 CPI sets up the RBNZ decision on 28 October.
Annual inflation is expected around 3.8-3.9%, close to the RBNZ's own 3.9% projection, and a hike is largely priced. A print at or above that keeps rate support intact. Overall skew: constructive vs AUD.
CAD
Oil above $100 does the heavy lifting for the loonie.
Monday's CPI is expected at 3.2% from 3.0%, and the BoC has signalled a significantly higher inflation forecast for its 28 October decision. Markets still price no change, given the soft labour market. A hot print would put a hike back into discussion, with Friday's retail sales a secondary input. Overall skew: firm vs USD and EUR.
Cross Asset Notes
Oil is the inflation risk and AI the growth risk.
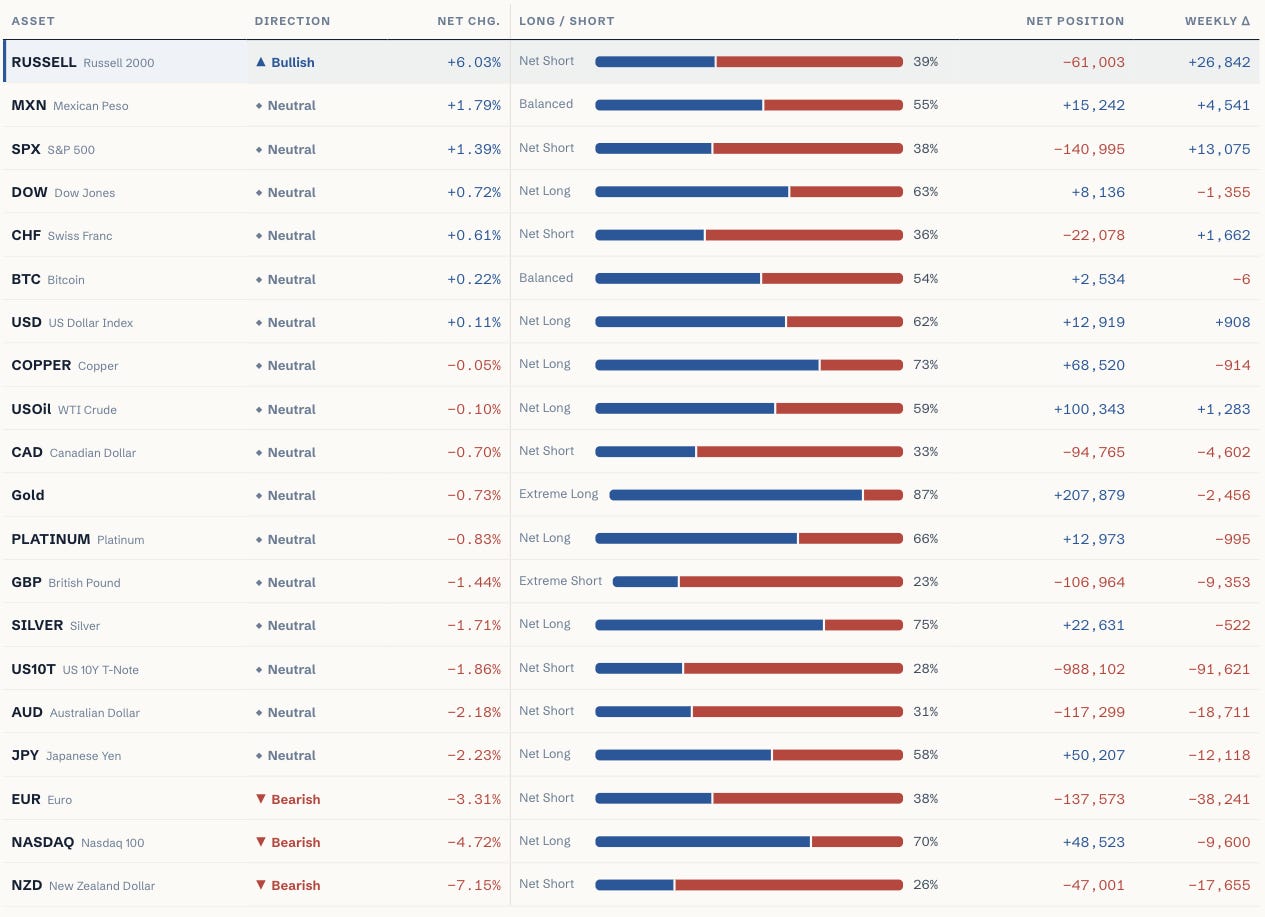
Brent settled near $110 and WTI above $100 after renewed attacks on Saudi export infrastructure. The S&P 500 lost about 2% on the week and the Nasdaq about 4.5% as the AI-linked chip sell-off deepened, while equities outside the US held up better. Gold holds a range near $4,170, as tighter Fed expectations offset haven demand. Copper trades close to its record high, and European gas stays elevated on the Middle East premium. Monday brings China's Q3 GDP (consensus 4.4%, prior 4.3%), and Wednesday the Tesla and Meta results. Wednesday and Friday set the tone this week, with UK CPI first and then the flash PMIs alongside the Moody's verdict on France.
Q-Score Overview
Institutional Positioning
Wishing you a successful week ahead,
David Gauch — Founder, Gauch Research